
 Published on and written by Cyril Jarnias
Owning a villa or apartment in Saint Barthélemy is a dream. But between an ultra-luxury market, prices among the highest in the world, and a banking system straddling French law and Caribbean realities, securing solid financing requires a real strategy. The whole challenge lies in understanding how the banks operating on the island work, what alternatives exist, and how to present an application capable of convincing in a market where most purchases are made… in cash.
Good to know:
Obtaining a mortgage loan on the island requires understanding the rules of French credit, adapting to the specifics of the local Caribbean market, and basing decisions on the available economic data for Saint Barthélemy.
An exceptional real estate market… with very large amounts
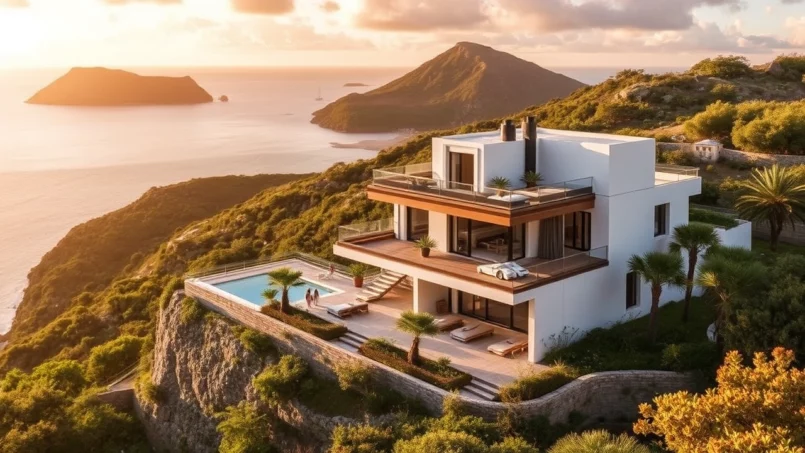
Before discussing mortgages, one must grasp the order of magnitude of the prices. Saint Barthélemy is a French overseas collectivity in the Caribbean, with an area of about 13.8 km² and just over 1,100 inhabitants for the main town, with around 10,000 residents broadly speaking. Land is extremely scarce, demand is strong, the clientele is international, and properties are predominantly high-end.
5000000
The price of a villa in Saint Barthélemy can reach €5 million, or even much more for the most exceptional properties.
New construction is also very expensive: costs are estimated around €8,000 per square meter. The entry ticket for a luxury residence is therefore colossal, which explains why the majority of transactions are settled in cash, without recourse to financing.
Nevertheless, the market remains dynamic and resilient. Even after the 2008 financial crisis, Hurricane Irma in 2017, or the COVID-19 pandemic, prices have maintained an upward trend, with only about twenty to thirty transactions per year, but for very high amounts. In this context, arriving with a project financed by a bank loan means being extremely well-prepared.
Is it possible to buy with a mortgage in Saint Barthélemy?
Legally, there are no restrictions on real estate purchases for foreigners. No residency status is required, regardless of the buyer’s nationality. Ownership is freehold and transactions are governed by French civil law, via a notary.
In terms of financing, the reality is more nuanced. Available information converges on several points.
Banks that can get involved
Several categories of players can finance a purchase in Saint Barthélemy.
First, banks present locally or in the region, often subsidiaries or branches of French groups:
| Bank / Institution | Type of Player | Real Estate-Related Services |
|---|---|---|
| Banque des Antilles Françaises | Local Bank | Accounts, Savings, Cards, Loans, Wealth Management Services |
| Banque Transatlantique | Local/International Bank | Wealth Management, International Operations |
| BNP Paribas (Gustavia branch) | Major French Bank | Accounts, Credit, Real Estate Financing, Transfers |
| Banque de Saint Barthélemy | Local International Bank | Various Banking Services, Mortgage Loans |
| Bred, Crédit Agricole, Crédit Martiniquais | Banks Present on the Island | Accounts, Savings, Credit, Mortgage Loans |
| Banco di Caribe | Regional Caribbean Bank | Residential and Commercial Real Estate Loans |
French banks from mainland France can also finance projects located in Saint Barthélemy, including for residents of the island or Saint-Martin. Groups like BNP Paribas, Crédit Agricole, or specialized institutions such as Crédit Agricole next bank for Swiss residents, are regularly mentioned among active lenders in France and its territories.
Tip:
Private banks, which typically target high-income clients, offer customized solutions, such as bullet loans (prêt in fine). This type of loan allows for repayment of only the interest during the loan term, with the principal paid in a lump sum at the end. In exchange for this flexibility, the bank often requires the client to entrust a portion of their assets to its management.
Finally, international private lenders complete the landscape, especially for complex projects, vacant land acquisitions, or when traditional bank credit is difficult to obtain. Some North American players finance, for example, bridge loan operations or projects on Caribbean land that deter traditional lenders.
Financing is possible… but far from systematic
In practice, obtaining a mortgage loan for a property in Saint Barthélemy remains tricky, especially for non-residents. The market is extremely liquid, sellers are reluctant to wait for a bank decision, and “cash” offers are very common. It’s not unusual to read that financing is “sometimes possible,” but often considered impractical.
Concretely, a foreign buyer can:
– apply to a local or regional bank present in Saint Barthélemy;
– go through a major French bank in mainland France;
– use a bank in their country of origin to finance a purchase abroad;
– or resort to a private loan or a wealth structuring arrangement via a private bank.
French nationals often benefit from favorable terms from French mainland banks, due to the close institutional link between the island and France. But non-residents, especially those from outside the EU, generally face stricter requirements, consistent with the broader French credit market.
What banks require to finance a property in Saint Barthélemy
Even though each institution has its own criteria, financing a property in Saint Barthélemy generally falls within the framework of French mortgage lending, adapted to a Caribbean context and very high amounts.
Down payment and loan-to-value ratio (LTV)
In France, banks traditionally lend between 70% and 85% of the property’s value, sometimes up to 100% for certain French residents under conditions. But for non-residents, especially from outside the EU/EFTA, LTV ratios are more often between 50% and 70%. In the case of Saint Barthélemy, where purchase prices are in the millions, we often see:
– a minimum down payment of about 30% for strong, resident profiles;
– higher requirements for non-European clients (down payments up to 50% or more).
Banks may also require, for foreign borrowers, a security deposit equivalent to several months’ payments (e.g., two years of installments) in a blocked savings account, in addition to the down payment.
Debt-to-income ratio and financial profile
French prudence rules apply: the total credit burden (mortgage, other loans, insurance) must not exceed approximately 35% of the household’s gross monthly income. Institutions consider different types of income: salaries, pensions, self-employment income (with three years of financial statements), existing rental income, recurring dividends, and other investment income.
Important:
For self-employed individuals, the presentation of at least three years of accounting records is generally required for a financing application. Furthermore, borrowers aged over 65 may face additional difficulties in obtaining a loan due to restrictions related to lenders’ borrower insurance policies.
Minimum amount and nature of loans
Mortgages in this type of market often involve high amounts. Many institutions set a minimum around €100,000, which rises significantly for non-resident profiles. Meanwhile, some private lenders or international banks position themselves for deals starting at several million, with “bridge” or bullet loans.
Available products include:
Types of Mortgage Loans in Saint Barthélemy
Discover the different financing solutions suited to acquiring a property on the island, each with its own characteristics.
Fixed-Rate Loan
Commitment for 15 to 20 years with a constant interest rate, offering great budget security. Often preferred for its stability.
Variable-Rate Loan
Rate indexed to Euribor, plus a bank margin typically between 1 and 2 percentage points.
Hybrid Loan
Combines an initial fixed-rate period for security, followed by a variable-rate period.
Flexible Payment LoanBullet Loan (In Fine)Bridge Loan

Cyril Jarnias is an independent expert in international wealth management with over 20 years of experience. As an expatriate himself, he is dedicated to helping individuals and business leaders build, protect, and pass on their wealth with complete peace of mind.
On his website, cyriljarnias.com, he shares his expertise on international real estate, offshore company formation, and expatriation.
Thanks to his expertise, he offers sound advice to optimize his clients' wealth management. Cyril Jarnias is also recognized for his appearances in many prestigious media outlets such as BFM Business, les Français de l’étranger, Le Figaro, Les Echos, and Mieux vivre votre argent, where he shares his knowledge and know-how in wealth management.





